
Banking
Agents that know KYC, card-scheme rules and the complaint clock.
Banking is 163 agents written for a retail and commercial bank. They work with the core banking system, the card management system and the loan origination system, and they leave credit, refunds and suspicious activity to the people accountable for them.
Built for
Every answer has to be right, fair and on record.
Built for a retail and commercial bank offering accounts, cards, personal and business loans, mortgages, payments, trade finance and wealth services through branches, relationship managers, mobile and internet banking. They serve retail customers, small businesses, corporate clients and wealth clients, and sell current and savings accounts, deposits, cards, personal loans, mortgages, SME and corporate lending, payments and cash management, trade finance, and investment products.
Complaints start a clock
An expression of dissatisfaction is a complaint, and the regulator’s handling timeline starts at once.
Refunds and disputes
Fee refunds, reversals and chargebacks follow the tariff, the refund policy and card-scheme time limits.
Pricing within the hurdle
Business loans must meet the risk-adjusted return hurdle, or go to the pricing desk or Credit Committee.
AML and secrecy
Sanctions, AML/CFT and customer data secrecy apply to every case, with no tipping-off.
The industry the agents know
Rewritten for Banking, not translated from a template.
- Its words
- KYC and customer due diligence, AML transaction monitoring, suspicious activity report, sanctions screening, credit scoring, probability of default, loan-to-value, debt-service ratio, non-performing loan, ECL provisioning, chargeback, dispute, net interest margin, cost-to-income ratio, liquidity coverage ratio, capital adequacy, relationship manager, core banking.
- Its systems
- the core banking system, the loan origination system, the card management system, the payments hub, the AML transaction-monitoring system, the KYC and onboarding platform, the CRM, the risk data warehouse, the internet and mobile banking platform.
- Its rules
- the banking regulator's conduct, complaint-handling and fair-lending rules; AML/CFT and sanctions, with no tipping-off of suspicious customers; Basel capital and liquidity requirements; IFRS 9 expected-credit-loss provisioning; card-scheme rules and PCI DSS; customer data secrecy and data protection; model risk management for every scoring model.
- Its numbers
- net interest margin, cost-to-income ratio, loan book growth, NPL ratio, cost of risk, deposit growth, digital adoption, customer onboarding time, complaint resolution time.
- Its approvers
- Credit Committee, Head of Retail Banking, Chief Risk Officer, MLRO (Money Laundering Reporting Officer), Compliance Officer, Relationship Director.
- How the departments map
- Sales is relationship management and product sales, Customer is the contact centre, branches' service desks, disputes and complaints, Product owns banking products and digital journeys, Engineering runs core banking, channels and payments, and Finance includes treasury, regulatory reporting and ALM.
Departments
Every department, one agent workforce.
163 agents across 11 departments, each handing its work to the right Banking approver.
| Department | What it covers | Agents | Link |
|---|---|---|---|
| Content | video, writing, imagery and localisation | 12 | See agents → |
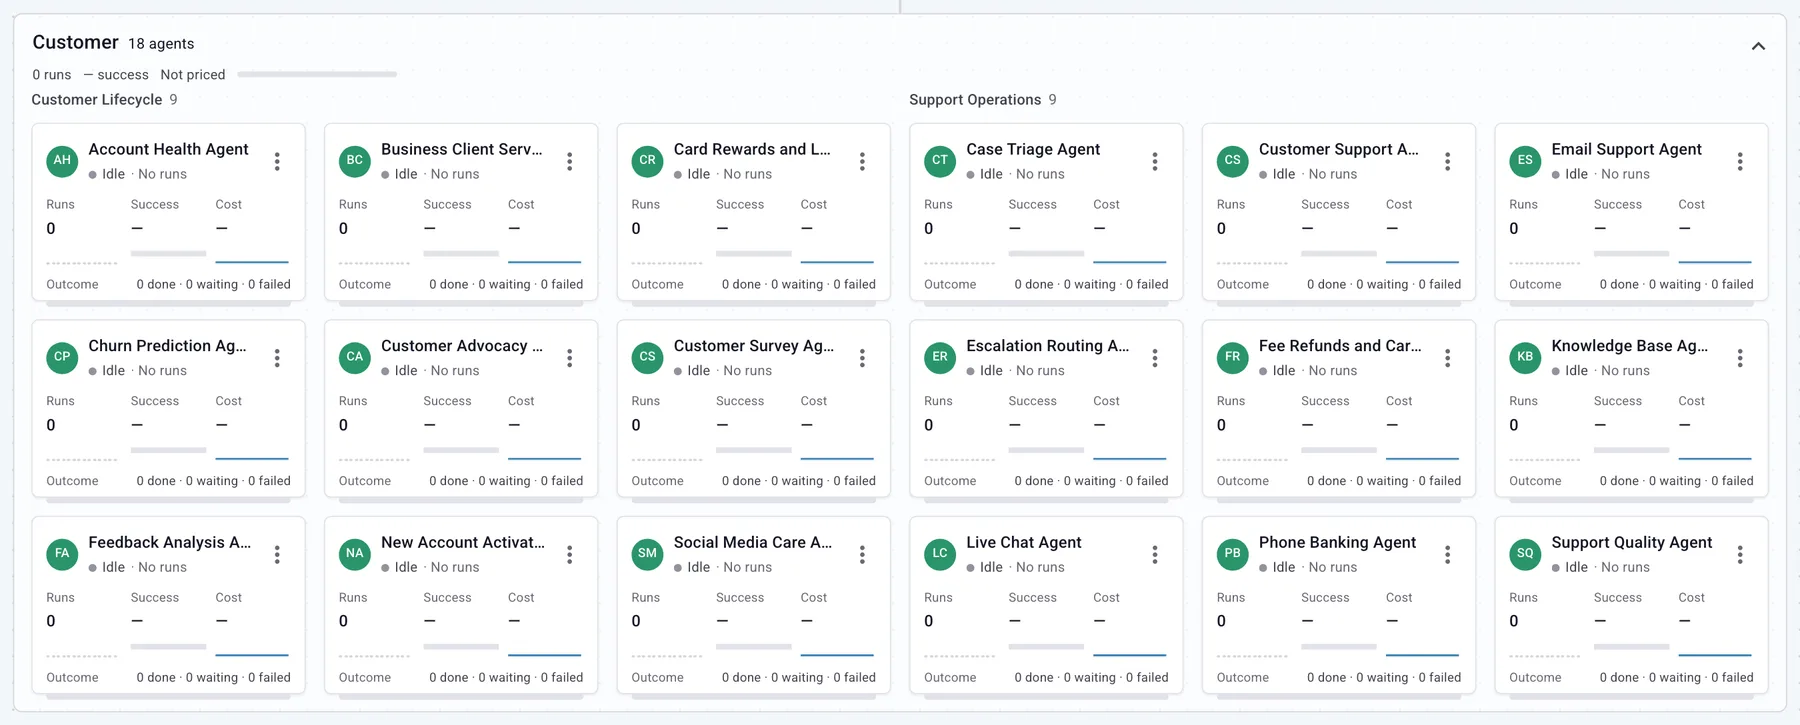
| Customer | support, service and retention | 18 | See agents → |
| Design | product, brand and experience design | 10 | See agents → |
| Engineering | building, running and securing the technology | 20 | See agents → |
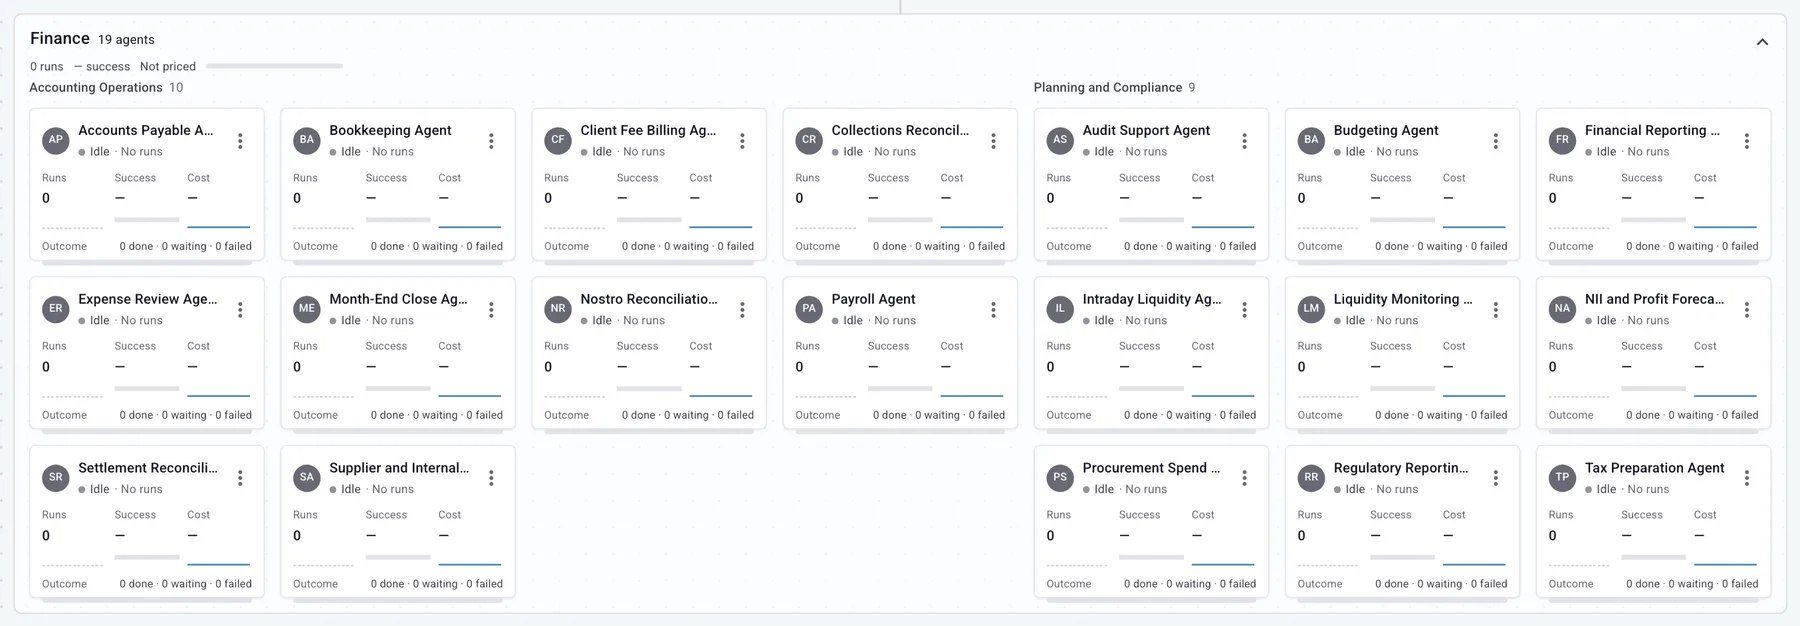
| Finance | bookkeeping, payables, receivables, payroll, close and planning | 19 | See agents → |
| HR | hiring, onboarding, people operations and learning | 14 | See agents → |
| Management | events, programmes, operations and leadership support | 12 | See agents → |
| Marketing | advertising, campaigns, SEO, social and lifecycle marketing | 18 | See agents → |
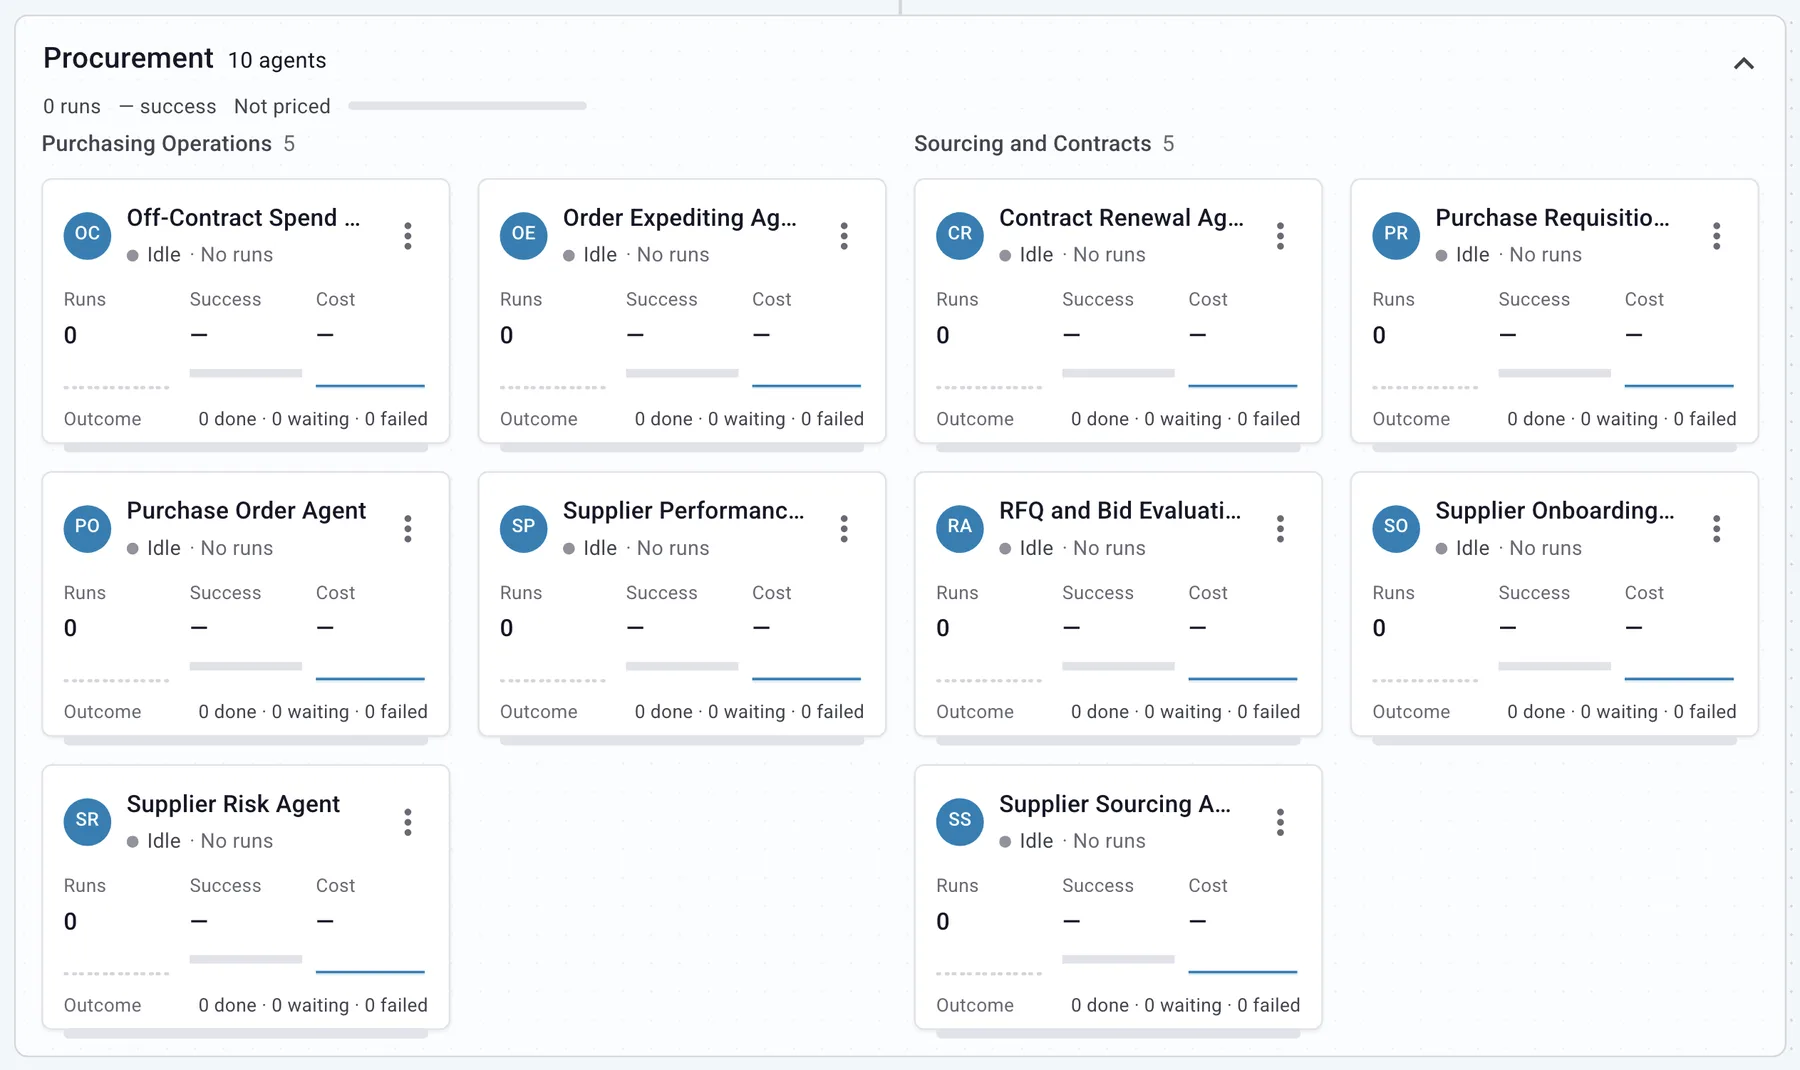
| Procurement | requisitions, sourcing, suppliers and contracts | 10 | See agents → |
| Product | planning, research, analytics and launches | 12 | See agents → |
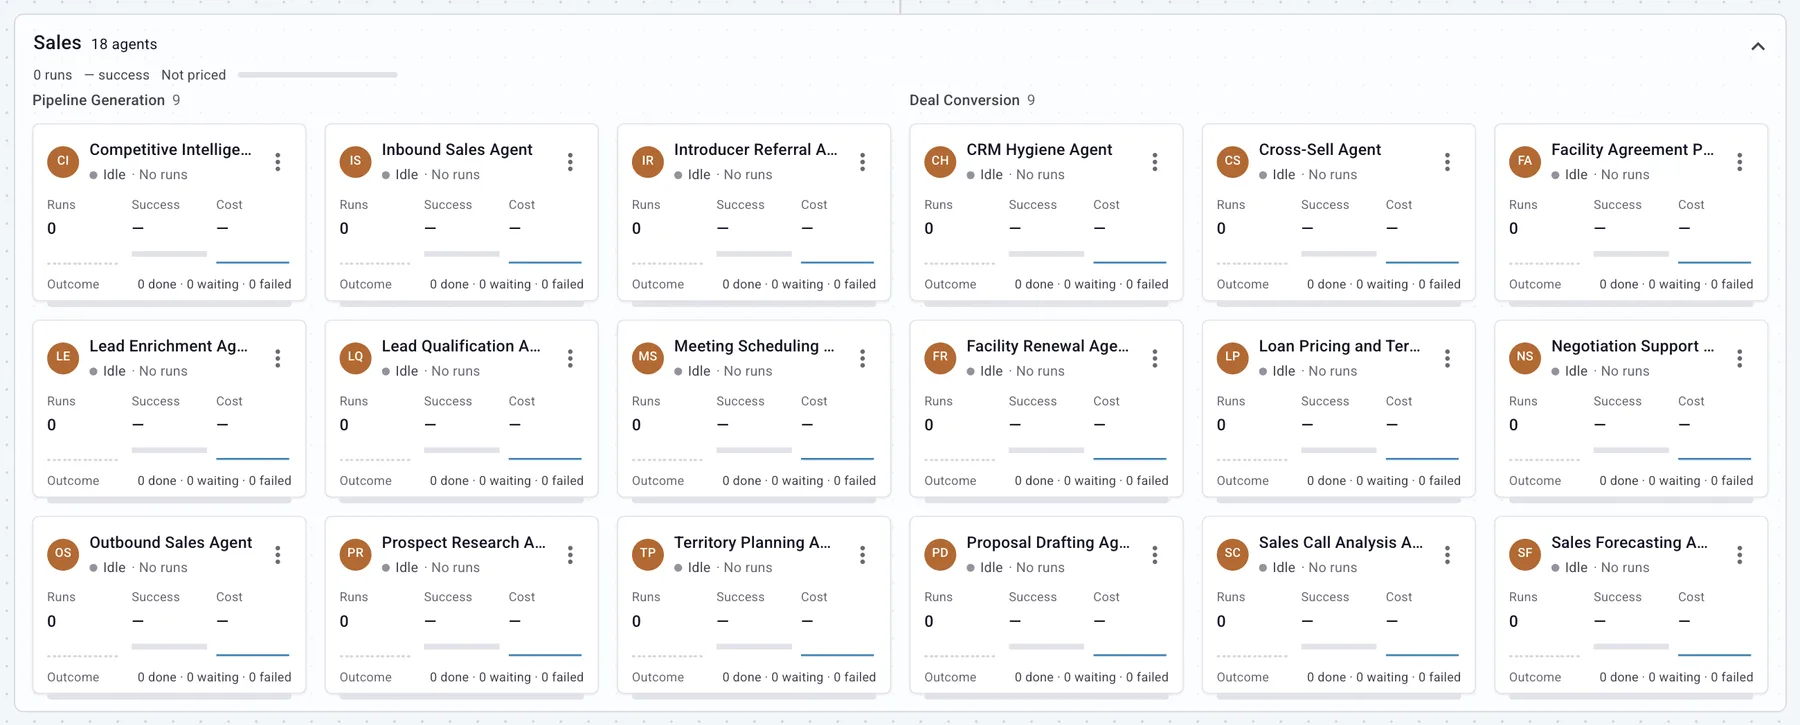
| Sales | pipeline, deals, proposals and account growth | 18 | See agents → |
AI agents
163 agents for a retail and commercial bank.
From a real run
The agent does the groundwork. A person makes the call.
This is what the approver sees: the agent’s finished work, waiting for a decision.
A frustrated, unverified retail customer reports a card payment declined abroad and asks for a written explanation and a refund of a foreign transaction fee of about 4.50 GBP. This is logged as a complaint, and a possible fraud block is referred to the fraud team. No records were available from the core banking system and the knowledge base returned nothing relevant, so the cause of the decline and the fee tariff are unconfirmed. If approved, the complaint is logged and acknowledged within 1 business day, the customer is asked to verify without sharing card secrets, and any refund above 0 USD is decided by you after the fee is confirmed against the verified account.
The approver can approve or edit and approve. Nothing is sent or changed until they do.
Inside the platform
What your teams see.
Use cases
Where Banking teams start.
Everyday banking questions, with the complaint clock respected
Declined cards, missing transfers and fee queries answered from verified records, with complaints recognised at once.
- Answers only once the customer is verified
- Dissatisfaction logged as a complaint, starting the handling clock
- Fraud and vulnerability routed to people
Fee refunds and card disputes
Refunds, reversals and chargebacks checked against the tariff, the refund policy and card-scheme rules.
- Repeat claims caught
- Card-scheme reason codes, time limits and evidence checked
- Nothing refunded without sign-off
Business loan pricing and term sheets
Facilities priced from risk grade, security and cost of funds, checked against the risk-adjusted return hurdle.
- Every deal checked against the return hurdle
- Pricing below the grid sent to the pricing desk or Credit Committee
- Indicative term sheets created on the application
How the work flows
From your systems to a decision, with a person in charge.
Core banking system
Card management system
Loan origination system
CRM
bank-card-disputes-story
Talk to us about Banking.
Tell us which service, lending or back-office work you want to improve. We’ll reply within one working day.
- A working session with a specialist for your industry
- Walk through the agents, their settings and their rules
- Agree which department to start with